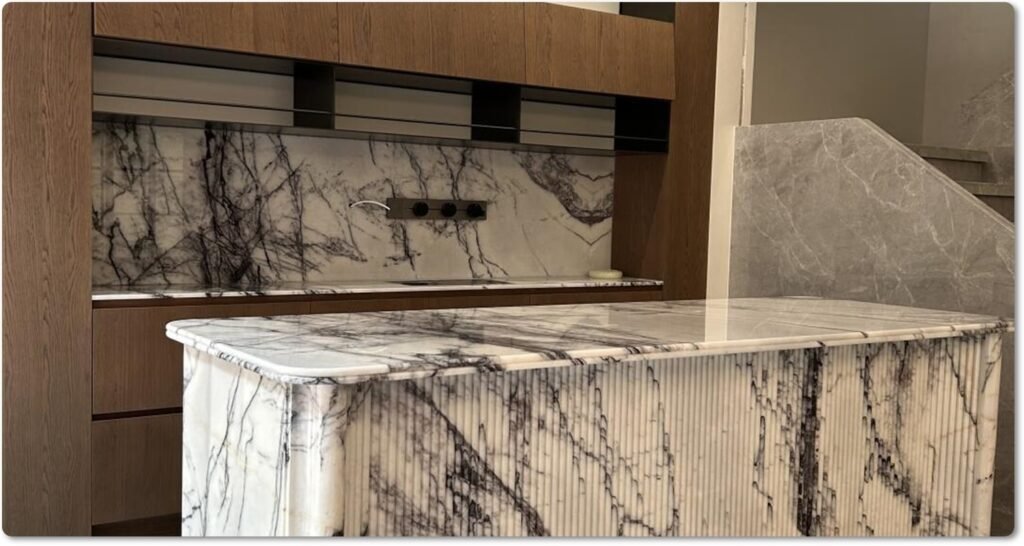
1. Executive Summary: How to Build a Competitive Marble Countertops Wholesale Business?
The marble countertops market offers several business models for companies serving residential construction, kitchen and bathroom renovation, interior design, hospitality, and commercial development. However, not every business needs to own a large slab warehouse, operate a fabrication workshop, or maintain a comprehensive showroom.
A successful wholesale strategy starts by selecting a business model that matches the company’s capital, customer relationships, operational capabilities, and tolerance for inventory risk.
A Marble Countertops Wholesaler generally focuses on purchasing products in commercial quantities and supplying fabricators, retailers, contractors, and other trade customers. A Marble Countertops Distributor develops a broader supply network, potentially supporting regional inventory, logistics, dealer relationships, and product availability. A Marble Countertops Reseller sells products to end customers or business buyers, often combining supplier sourcing with project coordination, customer service, and local installation partnerships.
These models can overlap. The appropriate structure depends on the company’s commercial objectives rather than its business title.
The five priorities for a stronger wholesale portfolio
Choose products around actual customer demand. Build the collection around documented sales opportunities, recurring specifications, and the needs of target customer segments.
Balance standardization and customization. Standard sizes and repeatable specifications can simplify purchasing, while custom fabrication can differentiate a business and serve higher-value projects.
Calculate total landed cost. Stone purchase prices alone do not determine profitability. Freight, import charges, handling, warehousing, local delivery, processing, breakage, and warranty expenses also matter.
Control inventory and documentation. Track individual slabs, batches, finishes, dimensions, photographs, availability, and customer commitments.
Develop a supplier relationship that supports repeat orders. Consistent specifications, clear communication, production verification, and realistic lead-time commitments are more useful than a low quotation without supporting evidence.
For importers and distributors sourcing from overseas factories, the central question is not simply, “What is the cheapest marble countertop?” It is, “Which product and supplier combination can deliver an acceptable contribution to the business after all relevant costs and risks?”
This whitepaper provides a practical framework for answering that question.
Who should use this guide?
This guide is intended for:
Natural stone wholesalers and importers.
Marble countertop distributors and regional dealers.
Countertop fabricators and installation companies.
Kitchen cabinet manufacturers and distributors.
Building-material retailers and showroom operators.
Interior design and architectural product suppliers.
Hospitality and multifamily project procurement teams.
Private-label brands exploring OEM or ODM manufacturing.
Businesses establishing a new Marble Countertops Collection.
The calculations and checklists are designed to be completed using company-specific quotations, shipping records, sales data, and operating expenses. They are not based on an assumed industry-average profit margin.
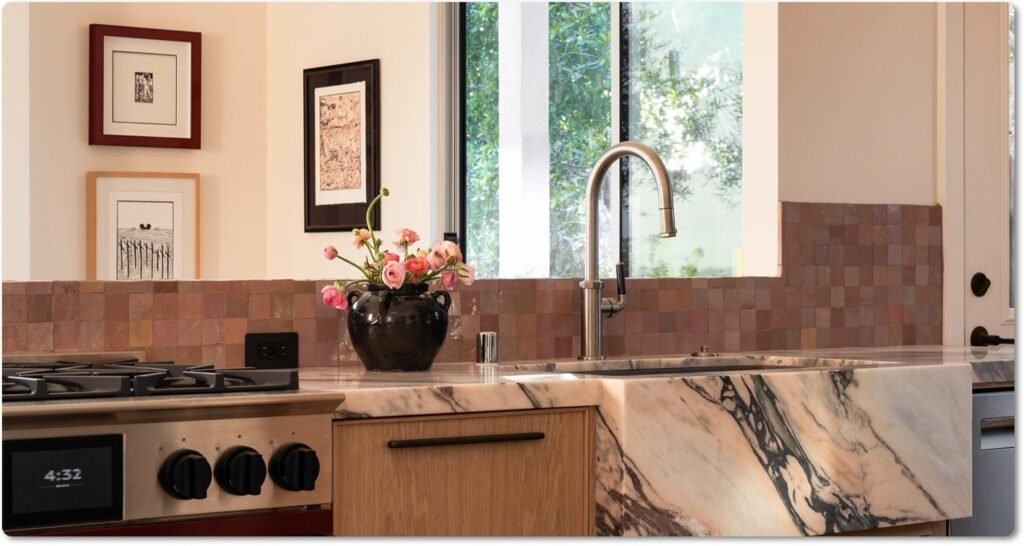
2. Scope and Definitions: Wholesale, Distribution, and Reselling
Before developing a product portfolio, buyers should distinguish the commercial activities involved in sourcing, storing, selling, and delivering marble countertops.
The terminology is not standardized across every market. One company may act simultaneously as an importer, wholesaler, distributor, and reseller.
2.1 What does a Marble Countertops Wholesaler do?
A Marble Countertops Wholesaler purchases stone products for resale to trade customers, often in quantities larger than individual consumer orders.
Its customers may include:
Local countertop fabricators.
Kitchen and bathroom retailers.
Cabinet companies.
Construction-material dealers.
Regional distributors.
Contractors and project buyers.
A wholesaler may hold inventory or purchase against confirmed orders. Its value proposition often includes competitive trade pricing, product availability, consolidated purchasing, reliable documentation, and access to multiple stone varieties.
Best suited to: Businesses with established trade customers, purchasing expertise, and sufficient working capital or supplier-supported fulfillment arrangements.
2.2 What does a Marble Countertops Distributor do?
A distributor typically coordinates supply across a defined territory or customer network. Depending on its business model, it may maintain warehouses, provide regional stock, develop dealer accounts, manage sales representatives, and coordinate delivery.
Distribution can involve additional responsibilities beyond purchasing and resale:
Regional product availability.
Inventory allocation.
Dealer pricing policies.
Sales forecasting.
Product training and documentation.
Returns and claims management.
Logistics and replenishment.
A distributor’s competitive advantage may come from reliable local fulfillment and customer relationships rather than simply obtaining a low factory price.
Best suited to: Businesses with regional reach, established trade relationships, and the operational capacity to manage inventory and replenishment.
2.3 What does a Marble Countertops Reseller or Dealer do?
A reseller or dealer sells marble countertops to other businesses or end customers. It may operate a showroom, an online catalog, a local sales office, or a project-based sourcing business.
A reseller does not necessarily own a fabrication facility or import products directly. It can cooperate with manufacturers, wholesalers, fabricators, and installers.
Its strengths may include:
Customer acquisition.
Product presentation.
Local market knowledge.
Project coordination.
Design assistance.
Customer support.
Installation partnerships.
A reseller can begin with a narrower portfolio and use supplier photographs, physical samples, technical specifications, and made-to-order production where commercially practical.
However, the reseller should clearly disclose who is responsible for measuring, fabrication, transportation, installation, and warranty service.
2.4 Comparison of the three business models
| Business factor | Wholesaler | Distributor | Reseller or dealer |
|---|---|---|---|
| Primary activity | Trade-volume purchasing and resale | Supply network and regional distribution | Sales to trade or end customers |
| Typical customer | Fabricators, dealers, contractors | Dealers, retailers, trade accounts | Homeowners, designers, contractors, businesses |
| Inventory strategy | Bulk or order-based | Regional stock and replenishment | Stocked samples, selected products, or project orders |
| Main competitive advantage | Purchasing efficiency and product range | Availability, logistics, and channel coverage | Customer relationships and product presentation |
| Capital requirements | Depends on inventory and credit terms | Potentially high when regional stock is maintained | Can be lower with made-to-order sourcing |
| Key operational risk | Purchasing too much or mispricing landed cost | Excess stock and channel complexity | Inaccurate quotations and dependence on suppliers |
| Typical differentiation | Range, price, consistency | Delivery capability and dealer support | Service, selection, design, and project coordination |
These descriptions are commercial models, not legal classifications. Contractual responsibilities, tax treatment, import obligations, and product-liability exposure must be assessed under the applicable jurisdiction.
2.5 Define the product being purchased
“Marble countertops” can describe several different deliverables:
Marble slabs intended for local fabrication.
Pre-cut countertop blanks.
Finished kitchen countertops.
Bathroom vanity tops.
Countertops with sink cutouts and faucet holes.
Custom islands and waterfall panels.
Backsplashes and matching wall panels.
Marble components supplied as part of a larger project.
These products are not commercially interchangeable.
A slab importer may be responsible for material selection, slab dimensions, and transport. A finished-countertop buyer may also need to specify finished dimensions, edge profiles, sink cutouts, surface finish, tolerances, packaging, and installation interfaces.
Before comparing supplier quotations, confirm that the quoted products have equivalent scopes.
2.6 Natural marble versus engineered stone
This guide focuses on natural marble countertops.
Natural marble is a stone whose mineral composition, veining, color, and physical properties vary by geological origin and individual block. Its appearance and performance should be evaluated using representative samples, available technical data, and agreed acceptance criteria.
Engineered quartz, porcelain, sintered stone, granite, and quartzite may compete for the same projects, but they have different material characteristics, processing requirements, and applicable technical standards.
Do not assume that test results, fabrication methods, care instructions, or performance claims for one material automatically apply to another.
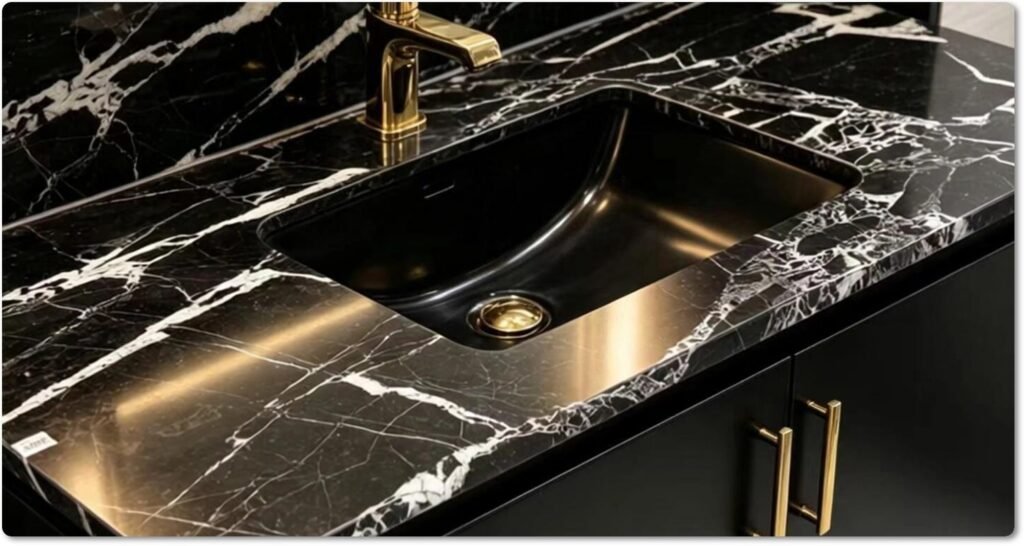
3. Technical Evaluation: Building the Right Marble Countertops Collection
A profitable Marble Countertops Collection is not necessarily the largest collection. It is the collection that serves defined customer segments while keeping purchasing complexity, inventory exposure, and quality-control requirements manageable.
The goal is to develop a portfolio with clear commercial roles.
3.1 Segment the collection by customer demand
Start by identifying the customer groups that generate the strongest purchasing opportunities.
| Customer segment | Potential product focus | Important buying considerations |
|---|---|---|
| Countertop fabricators | Slabs and fabrication-ready material | Dimensions, thickness, defects, yield, and handling |
| Cabinet companies | Standardized vanity tops and kitchen components | Repeatability, dimensions, cutouts, and delivery coordination |
| Residential retailers | Popular colors and selected finished products | Visual presentation, sample availability, and lead time |
| Hospitality buyers | Vanity tops, reception counters, and custom components | Specification control, batch planning, inspection, and replacement feasibility |
| Contractors and developers | Repeatable products for multiple units | Quantity, tolerances, scheduling, packaging, and total installed cost |
| Design-led brands | Distinctive marble and custom components | Visual consistency, documentation, finish quality, and customization |
| Regional distributors | Selected stock lines and project-specific materials | Replenishment, inventory turnover, and dealer demand |
Use actual inquiry records, sales history, lost-order reasons, and customer interviews to validate the portfolio. A material that attracts attention in a showroom is not automatically a profitable inventory item.
3.2 Develop three portfolio tiers
A practical portfolio can be divided into three tiers.
Tier A: Core products
Core products are the items most closely aligned with recurring customer demand.
They may include established white, beige, gray, or other commercially relevant marble selections, depending on the market.
For each core product, define:
Material identification and commercial name.
Available thicknesses and dimensions.
Surface finishes.
Edge and fabrication options.
Expected replenishment process.
Quality acceptance criteria.
Supplier and replacement arrangements.
Core products should be selected using evidence of repeat demand, not color popularity alone.
Tier B: Differentiation products
Differentiation products give the business a reason to be selected beyond price.
These might include distinctive veining, carefully selected bookmatched material, custom vanity designs, premium edge profiles, or coordinated marble components.
The business should assess whether customers will pay enough for the additional selection, handling, fabrication, and sales effort.
A distinctive material may generate a higher selling price but also require more time to sell, create more selection disputes, or produce greater cutting waste.
Tier C: Project-specific products
Project-specific products are purchased or fabricated for an identified customer requirement.
Examples include:
Custom kitchen islands.
Oversized vanity tops.
Multi-unit residential bathroom packages.
Reception counters.
Coordinated countertop and backsplash sets.
Special finishes and edge profiles.
Matched or bookmatched panels.
Project-specific purchasing can reduce speculative inventory exposure, but it requires accurate drawings, approved samples, clear tolerances, and realistic production schedules.
3.3 How to evaluate individual marble materials?
Each proposed material should be evaluated on both commercial appeal and technical suitability.
Visual characteristics
Record the following:
Base color and visible tonal range.
Veining pattern and direction.
Natural mineral concentrations.
Filled areas and repairs, where present.
Surface finish.
Variation between slabs or batches.
Suitability for the intended design.
Photographs should represent the actual available material as accurately as possible. For natural stone, one photograph cannot establish that every future slab will have an identical appearance.
Where color matching or vein continuity is important, obtain photographs of the actual slabs being offered and document the customer’s approval.
Physical characteristics
Request available technical information relevant to the intended application.
Depending on the material and specification, this may include:
Water absorption.
Bulk density.
Flexural strength.
Compressive strength.
Abrasion or wear-related properties where relevant.
Resistance to staining under defined conditions.
Suitability for the specified environment.
For U.S. projects, ASTM C503/C503M addresses marble dimension stone, while ASTM C97/C97M addresses absorption and bulk specific gravity of dimension stone. Buyers should verify the current editions, applicable scope, and actual test methods before placing these standards in a contract.
A test result is meaningful only when the tested material, method, laboratory, and acceptance criteria are understood.
Processing and fabrication characteristics
Natural marble can be sensitive to improper handling, unsupported spans, concentrated loads, aggressive cleaning products, and unsuitable installation conditions.
The supplier and fabricator should review:
Thickness and dimensional tolerances.
Edge profiles.
Sink and faucet cutouts.
Internal corners and narrow sections.
Support requirements.
Reinforcement, where appropriate.
Packaging and lifting methods.
Installation and maintenance requirements.
Fabrication details should be approved before production rather than left to interpretation after the material has been cut.
3.4 Standard products versus custom fabricated products
Standardized products and custom fabrication solve different commercial problems.
| Consideration | Standard products | Custom fabricated products |
|---|---|---|
| Product definition | Predetermined dimensions and specifications | Customer-specific drawings and specifications |
| Quotation process | Often simpler | Requires scope review and technical confirmation |
| Repeatability | Easier when material and specifications remain available | Depends on drawings, material, and production controls |
| Inventory | Can require finished-stock investment | May be produced against confirmed demand |
| Differentiation | Often based on price, availability, and service | Can include design, dimensions, and specialized fabrication |
| Main risk | Slow-moving stock and specification mismatch | Drawing errors, revisions, and production rework |
| Documentation | Standard specification sheets | Approved drawings, revisions, and inspection records |
A wholesaler should not assume that standard products always have better margins. Nor should a distributor assume that custom products always produce higher profits.
The right comparison uses the fully allocated cost, achievable selling price, sales effort, working-capital requirement, and risk of claims for each product category.
3.5 Build a product specification sheet
Every repeatable product should have a specification record containing:
Product code.
Material and commercial name.
Material identification, where available.
Nominal thickness.
Finished dimensions or slab dimensions.
Surface finish.
Edge profile.
Cutouts and fabrication details.
Dimensional tolerances.
Visual acceptance criteria.
Packaging method.
Country of origin and applicable trade documentation.
Care and maintenance guidance.
Warranty scope and exclusions.
Revision date.
For customized orders, attach the approved drawing and record all subsequent revisions.
A well-maintained specification sheet reduces misunderstandings between the buyer, factory, fabricator, logistics provider, and end customer.
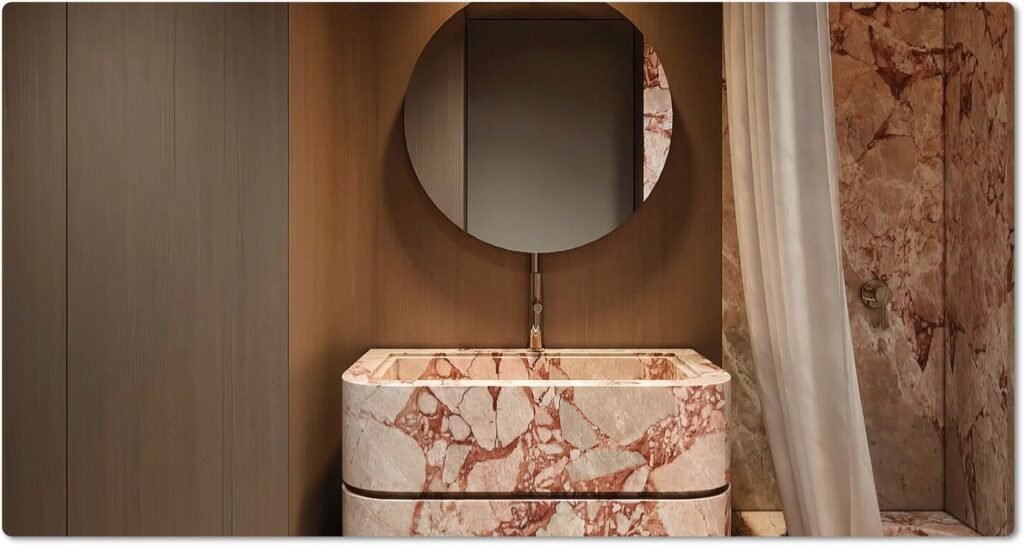
4. Procurement Checklist: From Supplier Search to Repeat Orders
Selecting a Marble Countertops Wholesaler or factory-direct manufacturer requires more than requesting a price list.
The buyer should evaluate whether the supplier can provide the required material, fabrication scope, production evidence, documentation, packaging, and communication.
4.1 Confirm the supplier’s actual role
Ask whether the supplier is:
A stone quarry operator.
A slab producer or processor.
A countertop fabricator.
An exporter.
A trading company.
A distributor combining several sources.
These roles are not mutually exclusive. A trading company may offer useful sourcing and quality-control services, while a factory may provide direct production capabilities.
The important question is whether the supplier can substantiate the capabilities relevant to your order.
Request appropriate evidence, such as:
Facility photographs or a live video inspection.
A description of the production workflow.
Samples of relevant fabrication work.
Equipment and process information where material to the order.
Recent, appropriately redacted inspection records.
References or documented project examples where available.
Export packaging photographs.
Sample commercial and shipping documents.
Do not assume that a supplier owns a quarry or manufactures every item simply because its website uses the words “factory direct.”
4.2 Evaluate quotation completeness
A usable wholesale quotation should identify:
Material.
Product dimensions and thickness.
Surface finish.
Edge profile and fabrication details.
Quantity and unit of measure.
Unit price and currency.
Packaging method.
Production lead time.
Payment terms.
Quotation validity.
Shipping terms and named place or port.
Inspection arrangements.
Treatment of defects and claims.
Available technical documentation.
Where two quotations cover different scopes, their prices should not be compared as if they were equivalent.
For example, a quotation for slabs without local fabrication is not directly comparable with a quotation for finished countertops including cutouts, edge processing, and protective packaging.
4.3 Request samples before committing to a large order
Samples help buyers assess appearance, finish, color, and general material suitability. They do not necessarily represent every slab in a future shipment.
For higher-value or multi-unit projects, consider a staged approval process:
Review initial samples.
Confirm the material and finish.
Review photographs of available slabs.
Approve the selected material or batch.
Approve fabrication drawings.
Inspect finished products against the agreed criteria.
Record acceptance before shipment where contractually appropriate.
For natural marble, acceptance criteria should distinguish normal geological variation from unacceptable defects.
4.4 Verify production and lead-time assumptions
Lead time should be divided into meaningful stages:
Material selection and confirmation.
Drawing approval.
Material preparation.
Cutting and fabrication.
Quality inspection.
Packing.
Export documentation.
Port handling and international transit.
Import clearance and local delivery.
A supplier’s stated production lead time does not necessarily include shipping, customs clearance, or final delivery.
For project orders, ask the supplier to confirm the production schedule in writing and identify dependencies such as drawing approval, deposit receipt, or material availability.
4.5 Procurement checklist
Before approving a supplier, confirm that the following items have been addressed.
| Checkpoint | Evidence or action | Status |
|---|---|---|
| Supplier identity | Verify legal business information and contracting entity | ☐ |
| Manufacturing capability | Confirm relevant processing capabilities | ☐ |
| Material suitability | Review identification and available technical data | ☐ |
| Product scope | Confirm dimensions, thickness, finish, and fabrication | ☐ |
| Visual approval | Record approved sample or slab-selection procedure | ☐ |
| Pricing | Confirm currency, quantity, and price basis | ☐ |
| Shipping | Clarify responsibilities under the agreed delivery terms | ☐ |
| Packaging | Approve protection, crates, labeling, and loading plans | ☐ |
| Quality control | Define inspection methods and acceptance criteria | ☐ |
| Documentation | Confirm commercial, customs, and product records | ☐ |
| Claims | Agree on notification periods, evidence, and remedies | ☐ |
| Replenishment | Establish a process for repeat orders and material changes | ☐ |
The checklist should be adapted to the order’s value, destination, product type, and contractual obligations.
5. Cost and Risk Factors: Calculating the True Economics of Wholesale Marble Countertops
A low purchase price does not necessarily produce a competitive selling price or a profitable transaction.
The buyer needs to calculate the total cost attributable to the product and compare it with the realistic net selling price.
5.1 Calculate the total landed cost
A practical model is:
Total Landed Cost = Purchase Cost + International Freight + Insurance + Import Duties and Applicable Taxes + Customs and Brokerage Charges + Port and Handling Charges + Inland Transportation + Other Import-Related Costs
This formula is a starting point, not a universal accounting definition. The treatment of recoverable taxes, financing charges, rebates, and other expenses depends on the business’s accounting policies and jurisdiction.
Import duties must be verified using the applicable tariff classification, country of origin, destination, and trade measures in force at the time of importation. Do not apply a duty rate based solely on a generic product description.
Worked example: Landed cost per countertop
The following figures are hypothetical and are provided only to demonstrate the calculation.
Assume a buyer purchases 100 marble vanity tops.
| Cost item | Hypothetical amount |
|---|---|
| Factory purchase cost | $12,000 |
| International freight and insurance | $2,400 |
| Customs brokerage and port handling | $600 |
| Import duty, if applicable | $600 |
| Inland transportation | $800 |
| Total landed cost | $16,400 |
The landed cost per unit is:
$16,400 ÷ 100 units = $164 per unit
This figure excludes any additional costs not included above, such as warehousing, local handling, finishing, order-specific inspection, breakage, or customer delivery.
If the goods require further processing before sale, the buyer must add those costs separately.
5.2 Calculate the fully allocated cost per unit
For a more complete view, use:
Fully Allocated Product Cost = Landed Cost + Applicable Local Handling + Additional Processing + Allocated Quality-Control Costs + Expected Breakage and Rework Costs + Other Attributable Costs
For example, suppose the 100-unit order above also incurs:
Local storage and handling: $500.
Additional processing: $700.
Order-specific inspection and documentation: $200.
Expected breakage and rework allowance: $200.
The total allocated cost becomes:
$16,400 + $500 + $700 + $200 + $200 = $18,000
The allocated cost per unit is:
$18,000 ÷ 100 = $180 per unit
These are illustrative assumptions, not industry benchmarks. A business should replace each number with actual invoices, historical records, or a clearly documented forecast.
The expected breakage and rework allowance is a budgeting provision. Actual claims and losses should also be recorded separately so the allowance can be evaluated over time.
5.3 Calculate gross profit and gross margin
Suppose the business sells each unit for $260, excluding separately collected sales tax.
Revenue:
100 × $260 = $26,000
Cost of goods sold for the 100 units:
100 × $180 = $18,000
Gross profit:
$26,000 − $18,000 = $8,000
Gross margin:
Gross Margin = (Net Sales Revenue − Cost of Goods Sold) ÷ Net Sales Revenue × 100%
Using the example:
($26,000 − $18,000) ÷ $26,000 × 100% = 30.77%
The result is a hypothetical gross margin based on the stated cost assumptions.
It is not net profit.
Depending on the company’s accounting policy, cost of goods sold may include or exclude certain expenses that have been included in this simplified landed-cost model. To avoid double counting, reconcile the calculation with the business’s actual inventory costing and accounting treatment.
5.4 Understand the difference between markup and gross margin
Markup and gross margin are different measurements.
Markup = (Selling Price − Cost) ÷ Cost × 100%
Gross Margin = (Selling Price − Cost) ÷ Selling Price × 100%
If the cost is $180 and the selling price is $260:
Gross profit per unit: $80.
Markup on cost: $80 ÷ $180 = 44.44%.
Gross margin on sales: $80 ÷ $260 = 30.77%.
A wholesaler that confuses markup with margin may set prices too low to cover the business’s operating expenses.
5.5 Calculate the required selling price
If the company has a target gross margin, the required selling price can be calculated as:
Required Selling Price = Fully Allocated Unit Cost ÷ (1 − Target Gross Margin)
For a unit cost of $180 and an illustrative target gross margin of 30%:
$180 ÷ (1 − 0.30) = $257.14
The business would need to sell at approximately $257.14 per unit to achieve a 30% gross margin under those cost assumptions.
This formula does not establish whether customers will accept the price. Market demand, competitors, product differentiation, service requirements, and customer willingness to pay must be evaluated separately.
5.6 Calculate the break-even sales volume
A product may generate a positive gross margin but still fail to cover the fixed costs of the business.
A simplified break-even formula is:
Break-Even Units = Fixed Costs ÷ Contribution per Unit
Contribution per unit is calculated as selling price minus variable costs per unit.
Suppose:
Selling price: $260.
Variable cost per unit: $180.
Monthly fixed costs attributable to the operation: $4,000.
Contribution per unit:
$260 − $180 = $80
Break-even volume:
$4,000 ÷ $80 = 50 units
The business would need to sell 50 units during the relevant period to cover the stated fixed costs, assuming the selling price, variable costs, and fixed-cost allocation remain unchanged.
This is a simplified operating model. It does not replace a complete profit-and-loss forecast or cash-flow analysis.
5.7 Account for inventory turnover and working capital
Inventory ties up cash until products are sold and customers pay.
A basic inventory turnover formula is:
Inventory Turnover = Cost of Goods Sold During the Period ÷ Average Inventory Value During the Period
For example, if annual cost of goods sold is $360,000 and average inventory value is $90,000:
$360,000 ÷ $90,000 = 4 inventory turns per year
An approximate inventory holding period can be calculated as:
Days Inventory Outstanding = Number of Days in Period ÷ Inventory Turnover
Using a 365-day year:
365 ÷ 4 = approximately 91 days
This example is illustrative. Use consistent inventory valuation methods and the appropriate period for your business.
High inventory turnover is not automatically better if it creates frequent stockouts or forces expensive emergency shipments. Conversely, low turnover may be reasonable for selected premium materials if the inventory strategy is intentional and financially sustainable.
5.8 Evaluate inventory risk by product
Track the following indicators for each SKU or material group:
Units received.
Units sold.
Current stock.
Days since last sale.
Average sales rate.
Gross profit generated.
Storage and handling cost.
Damage and rework history.
Customer commitments.
Replenishment lead time.
A useful management rule is to distinguish fast-moving core products from slow-moving specialty inventory.
For slow-moving products, consider smaller initial quantities, made-to-order sourcing, pre-selling, or requiring customer approval before committing to a large purchase.
5.9 Test the downside before placing an order
Use scenario analysis to understand what happens if the business does not achieve its expected selling price or sales volume.
For example, calculate the impact of:
A 10% reduction in selling price.
A 15% increase in freight cost.
A delay in customs clearance.
Higher-than-expected breakage.
A longer inventory holding period.
A customer postponing a project.
Currency movements between quotation and payment.
These percentages are hypothetical stress-test inputs, not forecasts of actual market movements.
A purchase should be evaluated against both the expected outcome and a plausible adverse outcome.
6. SKU Management and Product Documentation
A structured SKU system helps wholesalers manage product availability, quotations, inventory, and customer expectations.
Natural marble introduces an additional challenge: two products carrying the same commercial material name may not have identical veining, color, or visual characteristics.
6.1 Separate product identity from individual slab identity
A product SKU identifies a defined commercial product or specification.
A slab or batch identifier records a particular physical item or group of items.
For example:
Product family: White Marble.
Commercial material: Supplier-confirmed material name.
Thickness: 20 mm.
Finish: Polished.
Product code: WM-20-POL.
Batch code: BATCH-2026-001.
Slab code: SLAB-001-A.
The identifiers above are examples only. A business should use a consistent internal naming convention.
Do not use the product SKU alone to promise that future slabs will have the same appearance as the current stock.
6.2 What information should the inventory system contain?
At minimum, record:
| Data field | Purpose |
|---|---|
| SKU | Identifies the product specification |
| Material name | Records the commercial material identity |
| Supplier | Identifies the source |
| Batch or lot | Tracks the production or supply group |
| Slab identifier | Identifies an individual slab when relevant |
| Thickness and dimensions | Supports suitability and yield calculations |
| Finish | Confirms the surface specification |
| Quantity available | Supports quotation and allocation |
| Location | Identifies the warehouse or storage area |
| Cost basis | Supports inventory valuation and pricing |
| Images | Helps buyers review actual material |
| Quality status | Records inspection or release status |
| Reservation status | Prevents double-selling allocated stock |
| Receipt date | Supports inventory aging analysis |
A simple spreadsheet can work at the beginning. Businesses with many slabs, multiple warehouses, or frequent stock movements may need an inventory management system.
6.3 Manage photographs and sample records
Photographs are especially useful for natural stone, but they should be controlled.
For each material or slab, consider recording:
Photograph date.
Lighting and image conditions where relevant.
Slab or batch identifier.
Available dimensions.
Finish.
Current availability.
Whether the image shows actual stock or a representative sample.
Do not describe a representative image as an exact photograph of available inventory.
If a customer approves a specific slab, retain the approval record with the quotation or purchase order.
6.4 Establish a product change-control process
When the supplier changes the material source, finish, thickness, fabrication method, or packaging specification, the buyer should evaluate whether the change requires approval.
A practical process is:
Identify the proposed change.
Assess its impact on appearance, performance, cost, and lead time.
Update the specification or drawing.
Obtain buyer approval when required.
Record the effective date.
Retain the previous revision for traceability.
This is particularly important for repeat orders, private-label products, and projects with multiple delivery phases.
7. Inventory Planning, Sample Kits, and Showroom Merchandising
A showroom and sample program should help customers make decisions without forcing the business to purchase every product in finished form.
The objective is to support sales while keeping inventory exposure under control.
7.1 Use samples to qualify demand
A sample kit may include:
Selected marble varieties.
Finish comparisons.
Thickness information.
Edge-profile examples.
Product specification cards.
Care and maintenance information.
QR codes linking to current product documentation.
For natural stone, samples should communicate that color and veining may vary between pieces.
When appearance consistency is commercially critical, show actual slabs or approved production material rather than relying exclusively on small samples.
7.2 Design the showroom around buyer decisions
A useful showroom helps customers answer practical questions:
What materials are available?
Which colors fit the intended project?
What finishes can be supplied?
Can the product be fabricated to the required dimensions?
How will the selected stone be packaged and delivered?
What documentation is available?
What is the likely procurement lead time?
Arrange products by application, material, color family, or customer segment according to how buyers actually shop.
A showroom with fewer clearly documented options may be more effective than a large display with incomplete specifications.
7.3 Use digital merchandising to extend the collection
A distributor can present a broader collection online than it keeps physically in stock, provided availability is represented accurately.
Product pages can include:
Material overview.
Application guidance.
Available dimensions and thicknesses.
Finish options.
Actual slab photographs where available.
Custom fabrication capabilities.
Technical documents.
Sample request options.
Wholesale quotation forms.
Clearly distinguish stocked products, supplier-available materials, and made-to-order products.
This distinction prevents avoidable customer disappointment and reduces the risk of advertising inventory that is no longer available.
7.4 Establish inventory reorder points
A simple reorder-point formula is:
Reorder Point = Expected Demand During Lead Time + Safety Stock
For example, if expected demand is 20 units per week and replenishment takes four weeks, expected demand during lead time is 80 units.
If the business adds a hypothetical safety stock of 20 units, the reorder point becomes:
80 + 20 = 100 units
This is a simplified illustration. Actual safety stock should reflect demand variability, supplier reliability, storage capacity, stockout consequences, and the cost of holding inventory.
For unique marble slabs, a reorder point may be less useful than a project-specific procurement plan because the exact visual material may not be replaceable.
8. Pricing Structure, Order Consolidation, and Inventory Risk
Pricing should reflect the full commercial scope rather than simply adding a percentage to the factory quotation.
8.1 Create a consistent wholesale price structure
A company may maintain separate price calculations for:
Factory purchase cost.
Landed cost.
Fully allocated cost.
Wholesale selling price.
Distributor selling price.
Dealer or reseller selling price.
Project-specific quotation.
Customer delivery and installation.
The price structure should reflect actual responsibilities and services.
For example, a distributor holding local stock may incur warehousing and financing costs that do not apply to a reseller purchasing directly against a customer order.
Similarly, a supplier quoting finished vanity tops may include fabrication that a slab wholesaler does not provide.
8.2 Do not confuse gross margin with net profit
Gross profit is generally calculated as net sales revenue less cost of goods sold.
Net profit reflects additional revenues and expenses, subject to the company’s accounting policies, including relevant operating expenses, financing costs, taxes, and other items.
A business may report a healthy gross margin but still lose money because of:
Rent and warehouse expenses.
Salaries and sales commissions.
Marketing and customer acquisition.
Financing and interest.
Insurance.
Administrative expenses.
Unrecovered warranty claims.
Bad debts.
Currency losses.
Excessive inventory write-downs.
For management purposes, monitor both product-level economics and the overall profit-and-loss statement.
8.3 Evaluate order consolidation
Combining several products into one shipment can sometimes reduce average freight or handling costs, but the benefit depends on the actual freight quotation and shipment configuration.
Before consolidating orders, consider:
Container loading capacity.
Product dimensions and weight.
Packaging requirements.
Fragility and handling compatibility.
Delivery deadlines.
Customs classification and documentation.
Whether all products can be shipped together.
The cost of delaying ready goods.
The cost of holding completed products.
A consolidated shipment is not necessarily cheaper if one delayed item postpones the entire order or requires additional storage.
Request comparable freight quotations for the proposed shipment configurations before making the decision.
8.4 Control damage and claims risk
Marble countertops can be damaged during handling, loading, transit, unloading, fabrication, or installation.
A damage-prevention process should include:
Appropriate packaging and support.
Secure loading and cargo restraint.
Clear handling instructions.
Photographic records before dispatch.
Shipment and packing-list reconciliation.
Receipt inspection.
Prompt notification of visible damage.
Evidence retention for any claim.
The contract should identify who is responsible for packaging, cargo insurance, transport, unloading, inspection, and claim notification.
The applicable delivery term and named place should be agreed in writing. The responsibilities assigned by the chosen Incoterms® rule must be understood alongside the sales contract, insurance arrangement, and destination-country requirements.
8.5 Build a risk register
| Risk | Potential effect | Possible control |
|---|---|---|
| Uncertain material availability | Missed delivery or substitutions | Confirm actual stock and reservation status |
| Natural variation | Customer rejection | Approve samples or actual slabs |
| Incorrect dimensions | Rework and wasted material | Use approved drawings and inspection records |
| Freight increases | Reduced margin | Obtain updated quotations and scenario-test costs |
| Transit damage | Claims and replacement costs | Improve packing, insurance, and evidence collection |
| Slow-moving stock | Working-capital pressure | Use sales data and staged purchasing |
| Supplier delay | Project disruption | Track milestones and agree escalation procedures |
| Inconsistent repeat orders | Customer dissatisfaction | Maintain specifications and change-control records |
| Currency fluctuation | Cost uncertainty | Define quotation validity and payment currency |
| Customer nonpayment | Cash-flow problems | Assess credit exposure and payment terms |
The objective is not to eliminate every risk. It is to identify which risks are material, assign responsibility, and establish a practical response before an order is placed.
9. Supplier Diversification and Repeat Orders
A resilient wholesale business needs dependable supply without creating unnecessary complexity.
Relying on a single supplier can expose the business to production delays, material shortages, price changes, or disruptions. Working with too many suppliers, however, can increase specification inconsistency, administrative effort, and quality-control costs.
9.1 Build a supplier portfolio by function
Instead of selecting suppliers solely by price, classify them according to the products and capabilities they can reliably provide.
For example:
Core material suppliers.
Premium or specialty marble suppliers.
Standard vanity-top manufacturers.
Custom fabrication partners.
Backup sources for critical product categories.
Packaging and logistics providers.
Not every product requires multiple suppliers. A distinctive material or approved project-specific slab may have only one feasible source.
The purpose of diversification is to reduce unacceptable dependency, not to create a large supplier list for its own sake.
9.2 Evaluate the cost of changing suppliers
A lower quotation may be offset by:
New sample approval.
Revised product documentation.
Different visual characteristics.
Fabrication compatibility issues.
Additional inspection.
New packaging requirements.
Longer lead times.
Customer reapproval.
For repeat business, assess the total cost of switching rather than comparing unit prices alone.
9.3 Develop a repeat-order specification
For every important product, retain an approved reference containing:
Material identification.
Approved photographs or sample.
Dimensions and tolerances.
Surface finish.
Fabrication drawings.
Packaging requirements.
Inspection criteria.
Labeling and documentation.
Previous order records.
Any known limitations or approved deviations.
A repeat order should reference the approved specification and clearly identify what may have changed.
For natural marble, the reference should define the acceptable range of visual variation rather than promise absolute visual identity across different blocks or batches.
9.4 Establish supplier performance indicators
Review supplier performance periodically using indicators such as:
On-time production completion.
On-time shipment readiness.
Quantity accuracy.
Inspection pass rate against agreed criteria.
Damage and claim frequency.
Response time.
Documentation completeness.
Lead-time variation.
Resolution time for corrective actions.
Repeat-order consistency.
Use consistent definitions and a meaningful number of orders before drawing strong conclusions from the data.
A supplier scorecard is useful only when its indicators are tied to actual purchasing decisions.
10. Regulatory and Trade Compliance: What Wholesale Buyers Should Monitor
International marble countertop sourcing can involve product specifications, customs requirements, environmental rules, packaging obligations, chemical restrictions, and destination-market consumer or construction regulations.
The applicable requirements depend on the product, intended use, country of origin, destination, and contractual arrangements.
The following is a procurement-oriented overview, not a legal determination for any particular shipment.
10.1 Customs classification and import costs
Importers should verify:
The correct tariff classification.
Declared customs value.
Country of origin.
Applicable duties and trade measures.
Import permits or restrictions, where relevant.
Required commercial and transport documents.
Country-specific labeling or product requirements.
Do not assume that all marble slabs, fabricated countertops, and finished stone articles share the same customs classification.
The correct classification depends on the product’s characteristics and applicable tariff rules. Seek a binding or formal classification decision where appropriate.
For U.S. imports, consult U.S. Customs and Border Protection and the current Harmonized Tariff Schedule. For imports into other markets, consult the relevant customs authority.
10.2 Product standards and technical claims
ASTM standards can provide a basis for evaluating dimension stone when their scope is relevant.
Examples include:
ASTM C503/C503M: Marble dimension stone.
ASTM C97/C97M: Absorption and bulk specific gravity of dimension stone.
ASTM C170/C170M: Compressive strength of dimension stone.
ASTM C880/C880M: Flexural strength of dimension stone.
Before specifying any standard in a purchase order, verify the current edition, scope, test method, sample requirements, and acceptance criteria.
Not every project requires every test. Testing should be proportionate to the intended application and the project’s technical requirements.
Do not use a generic material certificate to claim that a finished countertop complies with every installation, structural, food-contact, or building-code requirement.
10.3 Environmental and chemical compliance
Buyers should distinguish the environmental characteristics of the natural stone itself from those of adhesives, resins, sealers, coatings, packaging, and other products used during fabrication.
Depending on the market and application, relevant considerations may include:
Chemical restrictions applicable to supplied articles or mixtures.
Safety data sheets for relevant chemical products.
Environmental declarations or product-specific documentation where required.
Packaging and waste obligations.
Requirements for certain buildings or public procurement projects.
Evidence supporting environmental marketing claims.
For European Union transactions, the applicability of REACH and other EU requirements should be assessed against the actual product and supply chain. Natural stone, treated stone, chemical mixtures, and composite products should not automatically be treated as having identical obligations.
Environmental claims should be specific and supported by evidence. Avoid describing a product as “eco-friendly,” “carbon neutral,” or compliant with a particular regulation unless the claim has been substantiated.
10.4 U.S. importer responsibilities
U.S. importers should establish the documentation and compliance obligations applicable to their particular goods.
Relevant authorities and resources may include:
U.S. Customs and Border Protection for customs entry and import requirements.
The U.S. International Trade Commission for tariff information.
The Occupational Safety and Health Administration for applicable workplace safety requirements.
The Environmental Protection Agency for environmental requirements within its jurisdiction.
State and local authorities for relevant building, environmental, and consumer-protection rules.
A supplier’s statement that goods are “export ready” does not replace the importer’s responsibility to verify applicable requirements.
10.5 Packaging, wood materials, and international transport
Stone shipments often require robust packaging because of the weight and fragility of the products.
Where wood packaging material is used in international trade, check the destination’s applicable requirements under the International Plant Protection Convention’s ISPM 15 framework.
Requirements depend on the packaging material and shipment circumstances. Confirm that applicable treatment, marking, and documentation requirements are satisfied.
The buyer should also verify container loading, weight distribution, securing arrangements, and safe unloading procedures with qualified logistics personnel.
10.6 Trade terms and contractual responsibility
Incoterms® rules published by the International Chamber of Commerce help define certain buyer and seller responsibilities, costs, and risk transfers.
For each order, document:
The selected Incoterms® rule.
The named place, port, or destination.
The applicable version.
Responsibility for export and import formalities.
Transport and insurance arrangements.
Delivery milestones.
Inspection and claim procedures.
Incoterms® do not replace the sales contract or determine every issue relating to ownership, payment, product conformity, or remedies.
For commercial transactions, legal and customs professionals should review requirements that materially affect the order.
11. Supplier Evaluation: Assessing EDG Stone and Other Potential Partners
A supplier should be evaluated against the products and services the buyer actually needs.
EDG Stone can be considered as a potential stone countertop manufacturing and export partner for businesses exploring natural marble countertops, wholesale sourcing, and custom fabrication.
As with any supplier, buyers should verify current capabilities, material availability, commercial terms, production scope, and documentation directly before placing an order.
11.1 Questions to ask a potential Marble Countertops Manufacturer
Product range
Which marble materials and product types can you currently supply?
Can you provide slabs, vanity tops, kitchen countertops, or other fabricated components?
Which thicknesses, dimensions, and finishes are available?
Can you support product selection for a defined customer segment?
Manufacturing and fabrication
Which cutting, edge-processing, and cutout operations can you perform?
Can you work from customer-approved CAD drawings?
How are drawing revisions controlled?
Which processes are performed in-house and which are subcontracted?
What inspection records can be supplied?
Quality and traceability
How is the material identified?
Can actual slabs be photographed before shipment?
How are dimensions and visible defects checked?
What acceptance criteria can be agreed before production?
How are nonconforming products and corrective actions handled?
Commercial terms
What quantities can be quoted?
Are there minimum order requirements for particular products?
How are samples priced and supplied?
How long are quotations valid?
What payment terms are available?
How are price changes handled between repeat orders?
Export and logistics
What packaging methods are available?
Can products be consolidated into a shipment?
What export documentation can be provided?
Which delivery terms can be quoted?
How are damage claims documented?
What production and shipment milestones can be confirmed?
11.2 What should a factory provide before a large order?
The appropriate evidence depends on the order, but a buyer may request:
A product specification sheet.
A formal quotation.
Material samples or photographs.
Approved fabrication drawings.
Relevant technical reports.
An inspection and acceptance plan.
Packaging specifications.
A proposed production schedule.
Export documentation requirements.
Written terms for defects, claims, and corrective actions.
Not every supplier will have every document in a standard format. The buyer should determine which records are essential and agree on their delivery before production begins.
11.3 Compare suppliers using a weighted scorecard
A weighted scorecard makes the evaluation more consistent.
The following weights are illustrative and should be adjusted to the business’s priorities.
| Evaluation category | Example weight |
|---|---|
| Product suitability and availability | 20% |
| Quality-control capability | 20% |
| Total landed cost | 20% |
| Production and delivery reliability | 15% |
| Documentation and compliance support | 10% |
| Communication and corrective action | 10% |
| Commercial flexibility | 5% |
| Total | 100% |
Rate each supplier against the same criteria, using a consistent scale and supporting evidence.
For example, a supplier with a low factory quotation but inadequate packaging evidence may be less competitive after the buyer considers damage exposure and replacement costs.
The scorecard supports a decision; it does not replace verification of mandatory technical or legal requirements.
12. Practical RFQ Template: Marble Countertops Wholesale and Distribution
Use the following template when contacting EDG Stone or another Marble Countertops Supplier.
The more complete the information, the easier it is to obtain quotations that can be compared on a like-for-like basis.
12.1 Buyer information
Company name:
Country and destination city:
Website:
Business type: Importer / Wholesaler / Distributor / Fabricator / Reseller / Contractor / Other
Primary customer segment:
Intended sales market:
Contact person:
Preferred currency:
12.2 Product requirements
Material name or requested color:
Natural marble or alternative material:
Product type: Slabs / Kitchen countertops / Vanity tops / Custom components / Other
Thickness:
Finished dimensions:
Quantity:
Surface finish:
Edge profile:
Sink and faucet cutouts:
Backsplash requirements:
Special fabrication requirements:
Approved drawing or reference image:
Acceptable visual variation:
Required technical documentation:
12.3 Commercial requirements
Requested unit price:
Price basis and currency:
Sample requirements:
Target order quantity:
Expected repeat-order frequency:
Minimum order requirements, if applicable:
Payment terms requested:
Quotation validity:
Packaging requirements:
Required production completion date:
Requested shipping date:
Preferred Incoterms® rule and named place:
Destination port or delivery address:
Required customs or product documents:
12.4 Quality and inspection
Required dimensional tolerances:
Material acceptance criteria:
Surface and edge quality requirements:
Permitted repairs or filled areas:
Inspection method:
Required photographs or inspection reports:
Packaging inspection requirements:
Claims notification process:
Replacement or corrective-action expectations:
12.5 Questions for the supplier
Please confirm:
Whether the requested material and product specifications are available.
Whether the quotation covers material only or finished fabrication.
Whether the material shown is actual available stock or representative imagery.
Whether samples can be supplied.
What production lead time applies after all approvals.
What technical and quality documents are available.
What packaging and loading methods are proposed.
Which export and shipping arrangements can be offered.
What minimum order conditions apply, if any.
How repeat orders and material changes are managed.
12.6 Supplier quotation comparison worksheet
| Item | Supplier A | Supplier B | Supplier C |
|---|---|---|---|
| Material and specification | |||
| Product scope | |||
| Unit purchase price | |||
| International freight | |||
| Duties and applicable taxes | |||
| Local handling and delivery | |||
| Processing and inspection | |||
| Expected damage and rework cost | |||
| Fully allocated cost per unit | |||
| Expected selling price | |||
| Expected gross margin | |||
| Production lead time | |||
| Documentation completeness | |||
| Quality-control evidence | |||
| Payment and delivery terms | |||
| Repeat-order suitability |
A comparison is only meaningful when each supplier is evaluated against the same specifications, quantities, cost assumptions, and delivery requirements.
13. Building a Long-Term Supplier Relationship
Long-term supplier relationships can improve coordination, reduce repeated specification work, and make purchasing decisions more predictable.
However, a long relationship should not replace quality verification or commercial discipline.
13.1 Begin with a controlled first order
For a new supplier, consider a first order that is large enough to test the relevant process but small enough to limit exposure if the results are unsatisfactory.
The appropriate quantity depends on the product, shipping economics, customer commitments, and risk tolerance.
Use the first order to evaluate:
Material conformity.
Fabrication quality.
Communication.
Packaging.
Documentation.
Production scheduling.
Delivery performance.
Claim handling.
Record the findings and incorporate any necessary improvements into subsequent orders.
13.2 Share forecasts without creating false commitments
A supplier may be able to plan production more effectively when the buyer provides an indicative demand forecast.
A useful forecast distinguishes:
Confirmed purchase orders.
Probable project opportunities.
Historical demand.
Seasonal expectations.
Unconfirmed sales leads.
Do not present speculative forecasts as guaranteed orders unless the parties have agreed to a binding commitment.
13.3 Establish a repeat-order review
Before each repeat order, confirm:
Material availability.
Current pricing.
Dimensions and specifications.
Visual variation.
Production capacity.
Packaging requirements.
Shipping arrangements.
Applicable compliance documentation.
A short pre-order review can prevent problems caused by assumptions carried over from a previous shipment.
13.4 Review total supplier value
The best supplier is not necessarily the supplier with the lowest unit price.
Evaluate the full commercial relationship, including product quality, documentation, lead-time reliability, communication, claim resolution, flexibility, and the cost of repeat purchasing.
A slightly higher quotation may be commercially preferable if it demonstrably reduces other costs or risks. Conversely, service claims should be supported by actual performance rather than marketing language.
14. Frequently Asked Questions: Marble Countertops Wholesale and Distribution
FAQ 1: How do I become a Marble Countertops Wholesaler?
Start by defining your target customers, product categories, destination market, and purchasing model. Research customer demand, request comparable factory quotations, calculate landed costs, and determine whether to hold inventory or buy against confirmed orders. Establish product specifications, quality acceptance criteria, packaging requirements, and a reliable delivery process before expanding your portfolio.
FAQ 2: How can I find a reliable Marble Countertops Manufacturer or factory?
Verify the supplier’s business identity, relevant production capabilities, material availability, inspection procedures, and export experience. Request samples, specifications, actual product photographs where appropriate, and a written quotation. Confirm which activities are performed in-house and which are subcontracted. A trial order can help establish whether the supplier meets your requirements.
FAQ 3: How do I calculate the wholesale price of marble countertops?
Calculate the purchase cost, international freight, insurance, import charges, handling, local transportation, processing, inspection, and other attributable costs. Divide the total by the appropriate saleable quantity to determine the unit cost. Then calculate gross margin using the expected net selling price and cost of goods sold. Include operating expenses separately when assessing net profitability.
FAQ 4: Should a marble countertops distributor keep inventory or use made-to-order purchasing?
The choice depends on demand, lead time, storage capacity, working capital, and product uniqueness. Stocking repeatable products may improve availability, while made-to-order purchasing can reduce speculative inventory exposure. A mixed strategy is often worth evaluating, but the decision should be based on actual demand and cost data rather than a universal rule.
FAQ 5: What should I check before importing wholesale marble countertops?
Confirm the material, dimensions, finish, fabrication scope, quantity, quotation basis, packaging, inspection criteria, production schedule, and shipping terms. Verify customs classification, origin documentation, applicable duties, destination-market requirements, and any relevant technical standards. Also agree on how damage, nonconformity, claims, and repeat-order changes will be handled.
15. Semantic Synthesis: How to Build a More Profitable Marble Countertops Business
The following synthesis consolidates the commercial principles that matter most when developing a marble countertops wholesale, distribution, or reseller operation. It is intended to provide a clear, self-contained explanation of the business model, selection logic, financial considerations, and purchasing strategy.
15.1 The central business principle: Profitability comes from portfolio design, not product count
A broad Marble Countertops Collection can attract more customer interest, but every additional material or specification can create costs associated with samples, documentation, purchasing, storage, marketing, and quality control.
The objective is to identify the smallest commercially effective portfolio that serves the target market while leaving room for specialized products when customer demand justifies them.
A practical portfolio often combines three functions:
Core products that support repeat purchasing.
Differentiation products that help the business stand out.
Project-specific products that address defined customer requirements.
These categories should be evaluated using sales evidence, product suitability, supplier reliability, and fully allocated costs.
15.2 How should a buyer choose between factory-direct sourcing and local distribution?
Factory-direct sourcing may offer greater access to production specifications, customization, and consolidated purchasing. However, the buyer may also need to manage international freight, import documentation, inventory, quality verification, and longer replenishment cycles.
Local distributors may offer faster availability, smaller purchase quantities, and more immediate customer support. Their prices may reflect the costs of maintaining local inventory and providing those services.
Neither model is automatically superior.
The correct comparison includes the total delivered cost, order size, required lead time, customization needs, payment terms, and the buyer’s ability to manage import and quality risks.
15.3 Why is landed cost more useful than the factory price?
The factory price represents only one part of the purchasing decision.
A product that appears inexpensive at origin can become less competitive after freight, import charges, local handling, processing, damage, and storage are included.
A meaningful sourcing decision therefore compares equivalent products at a consistent cost boundary.
For an importer, that boundary may be landed warehouse cost. For a reseller, it may include additional local processing and delivery. For a project contractor, the relevant comparison may extend to installation-ready cost.
The appropriate calculation depends on the buyer’s role and the responsibilities included in the quotation.
15.4 What creates value in custom marble fabrication?
Custom fabrication can differentiate a wholesaler or reseller by enabling products that match specific dimensions, layouts, edge profiles, and design requirements.
Its commercial value depends on whether the additional selling price compensates for drawing preparation, production complexity, material yield, inspection, packaging, and rework exposure.
The most important controls are clear drawings, revision management, approved material selection, defined tolerances, and documented acceptance criteria.
Customization should be sold as a controlled manufacturing service, not merely as a promise that any design can be produced without limitations.
15.5 What should buyers consider before committing to bulk inventory?
Bulk purchasing can consolidate orders and improve product availability, but it also ties up capital and increases exposure to slow-moving stock, material changes, and customer demand fluctuations.
Before purchasing, estimate expected sales volume, lead time, storage costs, cash requirements, and the consequences of selling below the planned price.
For visually distinctive natural marble, consider whether the inventory can be replenished with an acceptable appearance match. The availability of the same commercial material name does not guarantee identical veining or color.
A staged purchasing plan can be preferable when demand is uncertain or when each slab has a unique visual identity.
15.6 Which supplier capabilities matter most for repeat business?
Repeat business depends on more than production capacity.
Buyers need a supplier that can work from documented specifications, communicate changes, provide relevant inspection evidence, package products appropriately, and support a workable corrective-action process.
A useful supplier evaluation combines commercial performance with technical and operational evidence.
For EDG Stone and other potential manufacturing partners, buyers should request current product information, relevant fabrication details, formal quotations, packaging specifications, and confirmation of the capabilities required for their particular order.
15.7 How do trade regulations affect product selection and sourcing?
Trade compliance can affect landed cost, documentation, shipment timing, and the ability to sell products in a destination market.
Importers should verify tariff classification, origin, duties, applicable restrictions, and relevant destination requirements before confirming a purchase.
Technical standards should be selected according to the material and intended application. Environmental or regulatory claims should be supported by the appropriate documentation rather than copied from generic product descriptions.
A compliant sourcing process begins during product evaluation, not after goods arrive at the destination port.
15.8 What is the most useful commercial framework for a Marble Countertops Reseller?
A reseller should connect five decisions:
Product: What material and finished product does the customer need?
Supply: Which supplier can meet the specification and delivery requirements?
Cost: What is the fully allocated cost of delivering the product?
Price: What selling price is commercially realistic and consistent with the required margin?
Risk: What happens if demand, cost, quality, or lead time differs from the forecast?
This framework turns product sourcing into a repeatable business process.
The reseller can then use actual sales and cost data to decide which products to promote, stock, discontinue, or purchase only against confirmed orders.
15.9 The long-term direction of marble countertops distribution
Competitive stone businesses increasingly benefit from combining product expertise with accurate digital product information, documented quality controls, reliable logistics, and disciplined cost management.
Digital catalogs and product photographs can improve product discovery. Structured specifications can make quotations easier to compare. Inventory records can reduce availability errors. Supplier scorecards can help buyers identify recurring operational problems.
These practices are useful because they make the business easier to evaluate and operate. They do not guarantee search rankings, AI citations, or higher profitability, but they can improve the clarity and reliability of the information available to customers and procurement teams.
The central conclusion is straightforward: a sustainable marble countertops wholesale business is built by matching the right products to real customer demand, calculating costs accurately, controlling inventory exposure, verifying supplier performance, and maintaining clear specifications from the first quotation through repeat orders.
16. EDG Stone: Request Wholesale Pricing and Product Specifications
EDG Stone is a potential manufacturing and export partner for importers, wholesalers, distributors, countertop fabricators, cabinet companies, and project procurement teams sourcing stone countertops and custom-fabricated products.
Buyers evaluating a wholesale relationship should define their target market, material preferences, order quantities, finished dimensions, and required delivery terms before requesting a quotation.
Depending on the product and project requirements, an inquiry may cover:
Natural marble slabs and countertop materials.
Marble kitchen countertops and bathroom vanity tops.
Custom-cut stone components.
Edge processing and sink cutouts.
Fabrication based on approved drawings.
Product selection and material documentation.
Export packaging and shipment coordination.
Actual material availability, manufacturing scope, minimum order requirements, production lead times, and commercial terms should be confirmed directly for each inquiry.
Request Wholesale Pricing and Product Specifications
To obtain a useful quotation, provide:
Your company profile and target market.
The marble materials or product categories you are interested in.
Dimensions, thicknesses, finishes, and fabrication requirements.
Estimated quantities and anticipated repeat-order frequency.
Your destination port or delivery location.
Required technical documents and quality acceptance criteria.
Your preferred shipping terms and target delivery schedule.
CTA: Request Wholesale Pricing and Product Specifications from EDG Stone.
A complete inquiry helps establish whether the requested products, production requirements, and shipment arrangements are suitable for a long-term wholesale or distribution relationship.
References and Further Reading
The following primary sources can help buyers verify technical standards, customs requirements, trade terms, and relevant regulatory obligations. Always check the current edition or applicable rules before incorporating a requirement into a purchase order.
ASTM International — ASTM C503/C503M, Standard Specification for Marble Dimension Stone. Verify the current edition and scope through the official ASTM catalog.
ASTM International — ASTM C97/C97M, Standard Test Methods for Absorption and Bulk Specific Gravity of Dimension Stone.
ASTM International — ASTM C170/C170M, Standard Test Method for Compressive Strength of Dimension Stone.
ASTM International — ASTM C880/C880M, Standard Test Method for Flexural Strength of Dimension Stone.
U.S. Customs and Border Protection — Importing into the United States and customs compliance guidance.
U.S. International Trade Commission — Harmonized Tariff Schedule of the United States.
International Chamber of Commerce — Incoterms® rules and guidance on buyer and seller responsibilities.
International Plant Protection Convention — ISPM 15, Regulation of Wood Packaging Material in International Trade.
European Chemicals Agency — REACH legislation and guidance on applicable chemical requirements.
U.S. Occupational Safety and Health Administration — Applicable workplace safety standards and guidance.
U.S. Environmental Protection Agency — Relevant environmental regulations and compliance resources.
Official resources:
ASTM International: https://www.astm.org/
U.S. Customs and Border Protection: https://www.cbp.gov/
U.S. International Trade Commission: https://www.usitc.gov/
International Chamber of Commerce: https://iccwbo.org/
International Plant Protection Convention: https://www.ippc.int/
European Chemicals Agency: https://echa.europa.eu/
U.S. Occupational Safety and Health Administration: https://www.osha.gov/
U.S. Environmental Protection Agency: https://www.epa.gov/
Editorial note: The financial examples in this article are hypothetical calculations, not published industry averages. Regulatory and standards references are provided for verification; they do not establish that any particular product, shipment, or supplier automatically complies with a given requirement.